Good news for employers: Employment contracts with monthly wages of RM3,000 or below no longer need to be submitted to HASiL for stamping or endorsement.
There has been considerable confusion among employers and HR practitioners regarding the stamping of employment contracts following the changes to Malaysia's Stamp Act 1949.
The confusion was understandable.
Earlier guidance indicated that even employment contracts which qualified for stamp duty exemption still needed to be submitted to the Inland Revenue Board of Malaysia (HASiL/LHDN) for endorsement or an exemption certificate.
However, HASiL has now provided a much clearer position.
In its Media Statement dated 7 August 2026, HASiL clarified the stamp duty and endorsement treatment for employment contracts and other instruments falling under the exemption categories of the First Schedule to the Stamp Act 1949.
So, what does this mean for employers?
The treatment can now be simplified into two main categories:
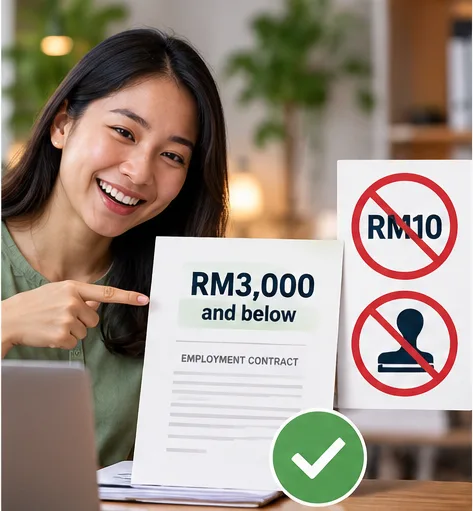
1. Monthly wages of RM3,000 or below
If the employment contract provides for monthly wages of RM3,000 or below, the contract falls within the relevant exemption under the First Schedule to the Stamp Act 1949.
The important clarification is that the exemption is now effectively both financial and administrative.
This means:
- No RM10 stamp duty is payable.
- The employer does not need to submit the contract for stamping.
- The employer does not need to submit it merely to obtain an RM0 exemption certificate.
- No endorsement is required for this category.
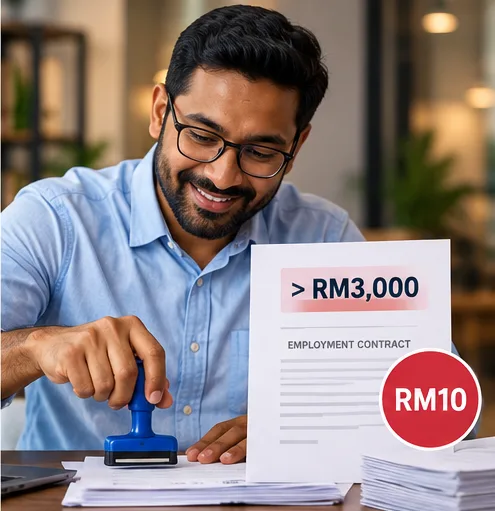
2. Monthly wages above RM3,000
The position is different where the employee's monthly wages exceed RM3,000.
The principal employment contract remains subject to RM10 stamp duty. The usual stamping timeline is also important. Employment contracts signed in Malaysia should generally be submitted for stamping within 30 days from the date of signing. Late stamping can result in penalties.
The contract should be submitted through the applicable stamping process and endorsed accordingly.
However, HASiL has also clarified that employers do not need to separately stamp every supporting document connected to the same employment relationship.
For example, where there is a principal employment contract setting out the terms and conditions of employment, the focus is on that principal employment contract.
Supplementary documents relating to the same employment arrangement are not automatically subject to separate stamping and endorsement under this clarification.
Why was there so much confusion?
The confusion arose partly because the concept of "exempt from stamp duty" and "not required to be submitted for endorsement" are not necessarily the same thing.
Previously, employers were told that certain exempt contracts could still be submitted to HASiL for endorsement to obtain confirmation of the exemption.
HASiL's latest clarification separates these categories more clearly.
Exemption vs General Exemption
This distinction is important.
Instruments under the relevant Exemption category
These do not require stamping or endorsement.
This includes employment contracts where monthly remuneration does not exceed RM3,000.
Instruments under the General Exemption category
These may still be exempt from stamp duty but may need to be submitted to HASiL for endorsement to establish that the instrument qualifies for the exemption.
Therefore, employers should not assume that every document described as "exempt" automatically means no endorsement is required.
The nature and category of the instrument must still be considered.
What should HR departments do now?
Employers should review their current employment contract process and ensure that HR and payroll teams are applying the latest HASiL position consistently.
A practical approach would be to:
1. Check the monthly wages stated in the employment contract
Identify whether the employee falls at or below RM3,000 or above RM3,000.
2. Separate principal contracts from supporting documents
Do not automatically process every HR document as a separate employment contract for stamping purposes.
3. Update your HR checklist
Your onboarding checklist should reflect the latest stamping requirements.
4. Review older internal guidance
If your HR SOP still states that every exempt contract must be submitted to LHDN for an RM0 exemption certificate, it should be reviewed.
5. Keep proper employment records
Even where stamp duty is not applicable, employers should continue to retain properly executed employment contracts as part of their employment records.
One important point: RM3,000 is not a blanket exemption from all employment-law requirements
The stamp duty exemption should not be confused with other statutory requirements relating to employment contracts.
The fact that an employment contract does not require stamping does not mean that the employer can dispense with a written employment contract or other employment documentation where required.
The exemption relates specifically to the stamp duty and endorsement treatment under the Stamp Act 1949.
The bottom line
The latest HASiL clarification makes the position considerably simpler for employers.
For employment contracts with monthly wages of RM3,000 or below:
No RM10 stamp duty. No submission for stamping. No endorsement merely to obtain an RM0 exemption certificate.
For employment contracts with monthly wages above RM3,000:
The principal employment contract remains subject to RM10 stamp duty and the applicable stamping/endorsement process.
This clarification should help HR teams reduce unnecessary administrative work while ensuring that employment contracts are processed correctly.
Official reference
Employers can refer to the HASiL Media Statement dated 7 August 2026 for the official clarification on stamp duty and endorsement treatment.
Note: This article is intended as a general HR compliance update and should not be treated as legal or tax advice. Employers should refer to the latest HASiL requirements when dealing with specific contracts or unusual employment arrangements.